
Paying family who help out: minimum wage, tax and the family exemption
If your café is a limited company, your grown-up son on the till is owed the minimum wage like anyone else. There is a family exemption, but HMRC's own manual says a company can't have a family, so it isn't open to you.
Most of the rules on family help work like that. Whether a relative is owed a wage, needs a council permit or has to be insured turns on who exactly the employer is, and often on whether they live with you. Small numbers matter too: ten hours a week at the National Living Wage falls £1.90 a week short of the level that builds a State Pension year.
The minimum wage, National Insurance and the Employment Allowance are UK-wide. The child employment rules here are for England and Wales: Scotland and Northern Ireland have their own, and byelaws vary by council. Scottish income tax bands differ. The employment rights listed are for Great Britain; Northern Ireland has its own rules on written statements and sick pay. Northern Ireland's employers' liability law has the same family exemption.
Three set-ups, and the question that changes the answers
The usual ones: a partner or spouse doing the books or a couple of shifts, a teenager at weekends on the till, and a parent, sibling or in-law covering when you're short.
If you're a sole trader, the employer is you: a person, with a family and a home. In a partnership, it's the partners. In a limited company, it's the company, which has neither. Three rules turn on that, each differently:
| Rule | Sole trader | Partnership | Limited company |
|---|---|---|---|
| Minimum wage family exemption | Can apply, if all three conditions are met | Not settled: ask HMRC or Acas | Doesn't apply, says HMRC |
| Employers' liability family exemption | Can apply, if every employee is a listed relative | Less clear: ask your broker | Doesn't apply, says HSE |
| Employment Allowance single-director rule | Doesn't apply | Doesn't apply | Applies |
A spouse who is a genuine partner in a partnership isn't your employee at all. They share the profits, so the minimum wage question doesn't arise.
The minimum wage family exemption, word for word
The National Minimum Wage Regulations 2015 have two family exemptions. Regulation 57 covers work in the family household. The café one is regulation 58, which takes work "in relation to an employer's family business" out of the minimum wage if the worker:
- "is a member of the employer's family",
- "resides in the family home of the employer", and
- "participates in the running of the family business".
All three. GOV.UK's eligibility guidance prints the household version of the third condition under its family business heading, so go by the regulation.
The condition people miss
The family member has to live with you. An adult son with his own flat or a mother across town doesn't qualify for it, however much family they are.
"Member of the employer's family" isn't defined in the Regulations or HMRC's manual, so for an unmarried partner or an in-law, ask HMRC or Acas. Whether a teenager on the till "participates in the running" of the business is a judgement call too: treat it as arguable, not safe.
Limited companies can't use it
HMRC's National Minimum Wage Manual is blunt: "A limited company is a legal entity in its own right and cannot be considered to have a family, to be a member of a family or to own a family home." In a company, a relative who is a worker is owed the minimum wage for their age like anyone else. For partnerships I couldn't find an HMRC statement either way.
The exemption also does less than people think: it switches off the minimum wage and nothing else.
"They're just helping out"
The voluntary worker exemption covers people working for "a charity, a voluntary organisation, an associated fund-raising body or a statutory body", paid nothing beyond expenses and, at most, subsistence or reasonable accommodation. A profit-making café isn't on that list.
The same GOV.UK guidance says "The job title or label an individual is given is not conclusive". Someone on the rota, expected to turn up and given a few notes when it's busy, is very likely a worker, the same status question as the self-employed weekend baker who turns out to be a worker. HMRC's notice of underpayment adds a penalty "at 200% of the underpayment for each worker".
Children who help in the family café
GOV.UK says "School-aged children are not entitled to the National Minimum Wage", so for a child still at school the family exemption is irrelevant. The child employment rules are what matter, paid or not.
Section 30 of the Children and Young Persons Act 1933 says that a person "who assists in a trade or occupation carried on for profit shall be deemed to be employed notwithstanding that he receives no reward for his labour". Bath and North East Somerset Council lists "Helping out in the family shop or restaurant (minding the till, taking orders or stocking shelves, for instance)" as employment, with the permit for the employer to get.
So the rules for school-age staff apply to family in full: a minimum age of 14 (13 in some council areas), the permit where your council requires one, no work in the kitchen, nothing before 7am or after 7pm, the Saturday and term-time hours caps, and an hour's break after four hours.
In England a child stops being of compulsory school age on the last Friday in June if they'll be 16 by the end of the summer holidays. From then the minimum wage applies: £8.00 an hour for under-18s from April 2026, £8.31 from April 2027, unless the family exemption genuinely covers them.
Paying a partner properly
Paying a partner or spouse a wage is ordinary and allowable. HMRC's Business Income Manual says "where there is equal pay for equal value the amount paid is fully allowable, notwithstanding any connection between payer and recipient."
The risk is overpaying. HMRC looks at whether pay "exceeds a reasonable level of the reward for the value of the work undertaken", and its manual page on paying friends and relatives asks whether pay is "commercial and commensurate with the duties undertaken". In practice: real work, real hours, a rate you could defend paying a stranger, and a note of what they do.
Payroll, the same as anyone
You must register for PAYE if anyone is "paid £96 or more a week" (there are other triggers), report pay to HMRC on or before each payday, and give a payslip showing gross and net pay. The 2026/27 figures, from HMRC's rates and thresholds for employers:
| Threshold, 2026/27 | Weekly | Monthly | Yearly |
|---|---|---|---|
| Lower earnings limit | £129 | £559 | £6,708 |
| Secondary threshold (employer NI at 15% above it) | £96 | £417 | £5,000 |
| Primary threshold (employee NI at 8% above it) | £242 | £1,048 | £12,570 |
| Personal allowance | £242 | £1,048 | £12,570 |
The £1.90 a week that can cost a pension year
Earnings between £129 and £242 a week from one employer are, says the State Pension guide, "treated as having paid National Insurance contributions". Paid at that level all year, that's a qualifying year with no employee NI paid. It takes 10 qualifying years to get any new State Pension and 35 for the full amount.
The catch: ten hours a week at the £12.71 National Living Wage is £127.10, £1.90 a week short of £129. No qualifying year from this job, though you still pay employer NI above £96 a week. The test is per pay period, so monthly it's £550.77 against £559.
Lifting a partner to £129 a week, or £12.90 an hour, costs £1.90 x 52 = £98.80 a year in pay, plus £98.80 x 15% = £14.82 in employer NI: £113.62 in all. The year it buys is worth up to £241.30 / 35 = £6.89 a week of State Pension (rounded), if their record would otherwise miss it. Check their National Insurance record first: they may get the year another way, through credits or voluntary contributions.
Employer NI and the Employment Allowance
The Employment Allowance takes up to £10,500 off an eligible employer's NI bill in 2026/27. An eligible sole trader or partnership can set the employer NI in the example below against it, unless the rest of the payroll has used it up.
Limited companies have an extra rule. GOV.UK says: "If your company has only one director, they must not be the only employee liable for secondary Class 1 National Insurance." HMRC's single-director guidance adds that "The decisive factor is that the additional employees must be paid above the Secondary Threshold."
That's how the rule works, not a reason to put anyone on the payroll: the pay must still be for real work at a commercial rate. Ask your accountant how it applies to you.
Dividends to a spouse
The other route people hear about in a company is giving a spouse shares. A dividend needs no work and builds no State Pension year.
HMRC's settlements legislation can tax income as yours where an arrangement diverts it to someone else to save tax, and a gift between spouses is caught if it is "wholly or substantially a right to income". In HMRC's own example, two shareholders give their wives shares with "no voting rights and no assets in a winding up", and the dividends are taxed as the husbands' income. Ask your accountant before you do anything with shares.
Same rights as anyone else
A relative who is an employee or worker gets:
- A written statement of their main terms on or before day one, whatever their hours.
- 5.6 weeks' paid holiday.
- Statutory Sick Pay from the first day of absence, if they're classed as an employee, at the lower of £123.25 a week or 80% of average weekly earnings.
- A pension assessment. Automatic enrolment covers workers aged 22 to State Pension age earning over £10,000 a year, and anyone aged 16 to 74 earning more than £120 a week who asks to join gets your contribution. The Pensions Regulator says a director without an employment contract is "always exempt".
You owe them a right to work check before day one, too. I can find no exception for relatives in the Home Office's employer guide, so check everyone you employ.
Insurance: the exemption that stops at the company
The general rule, as the café insurance guide says, is employers' liability cover from your first employee: at least £5 million, with fines of up to £2,500 a day without it. The family exemption is narrow.
Section 2(2)(a) of the Employers' Liability (Compulsory Insurance) Act 1969 says you needn't insure "in respect of an employee of whom the employer is the husband, wife, civil partner, father, mother, grandfather, grandmother, step-father, step-mother, son, daughter, grandson, granddaughter, stepson, stepdaughter, brother, sister, half-brother or half-sister". Three limits:
- The list is exact. Unmarried partners, in-laws, nieces, nephews, aunts, uncles and cousins aren't on it.
- In practice it's all or nothing. HSE's guide to the Act describes it as being for family businesses, "if all of your employees are closely related to you". One Saturday employee from outside the family and you need a policy.
- Not for companies. HSE: "this exemption does not apply to family businesses which are incorporated as limited companies". The GOV.UK page leaves that out. There is a separate, narrow exemption for a company whose only employee owns half or more of its shares.
Northern Ireland's 1972 Order has the same list, and nibusinessinfo applies the same company limit. Exempt isn't protected, though: a relative hurt on the slicer is still hurt. Whether to insure anyway, or whether any exemption fits you, is a question for your broker.
What unpaid family hours really cost you
Paid or not, family hours are labour. Leave them out and the business looks better than it is, until one of them stops.
An illustrative example: in a hypothetical café, a partner over 21 does 10 hours of admin a week and a 16-year-old who has left school does 6 hours on Saturdays. The assumptions:
- Both are costed at the minimum wage, a floor: a bookkeeper would cost more.
- Yearly figures are 52 weeks of pay, holiday taken inside them.
- Employer NI uses the annual £5,000 threshold, so per-period payroll will differ by a pound or so.
- The April 2027 column uses the announced rates with today's threshold and 15% rate.
| Line, illustrative | April 2026 rates | April 2027 rates |
|---|---|---|
| Partner, weekly | 10 x £12.71 = £127.10 | 10 x £13.21 = £132.10 |
| Partner, yearly (x 52) | £6,609.20 | £6,869.20 |
| 16-year-old, weekly | 6 x £8.00 = £48.00 | 6 x £8.31 = £49.86 |
| 16-year-old, yearly (x 52) | £2,496.00 | £2,592.72 |
| Employer NI, partner | (£6,609.20 - £5,000) x 15% = £241.38 | (£6,869.20 - £5,000) x 15% = £280.38 |
| Employer NI, 16-year-old | £0.00 | £0.00 |
| Total a year | £9,346.58 | £9,742.30 |
The 16-year-old's pay is under £96 a week, and under-21s carry no employer NI below £967 a week anyway. Neither is automatically enrolled: the partner earns under £10,000 and the 16-year-old is under 22. If the partner asks to join, the minimum employer contribution is 3% of (£6,609.20 - £6,240) = 3% x £369.20 = £11.08 a year.
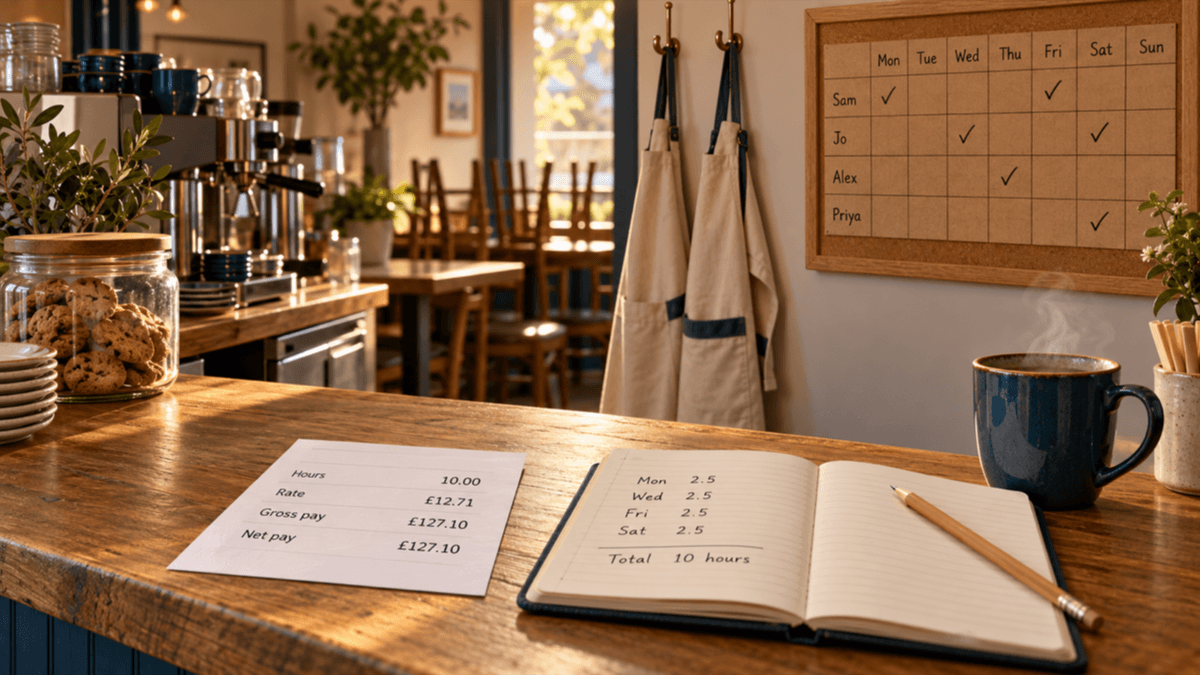
Assuming no other income, neither pays income tax or employee NI on this job, so the partner's payslip reads 10 hours at £12.71, gross pay £127.10, net pay £127.10. Between the columns the total rises £395.72, or 4.2%.
In your wage percentage
Say the café's turnover is £240,000 a year ex VAT and its fully loaded wages £72,000: a wage percentage of £72,000 / £240,000 = 30.00%. Count the family hours at April 2026 rates and it's £81,346.58 / £240,000 = 33.89%. At April 2027 rates, holding the rest still, it's £81,742.30 / £240,000 = 34.06%.
For a bakery or counter-led café, the 2026 wage percentage benchmarks call 28 to 33% healthy and 33 to 37% tight but workable. The unpaid hours are the difference.
In what the café is worth
A buyer doesn't inherit your partner's unpaid admin. What your café is worth is adjusted profit times a multiple, roughly 1.5 to 2.5 for a small owner-run café, and a careful buyer will cost those hours and take them off: £9,346.58 is £14,019.87 at 1.5 times, £18,693.16 at 2 times and £23,366.45 at 2.5 times. At a market rate, more.
Family on the payroll who don't really work there get added back. Family who work but aren't on the payroll come off, and a lender may ask the same.
This week
- List everyone who helps: relationship, whether they live with you, and who employs them.
- If you rely on the family exemption, write down why all three conditions are met. In a limited company, it doesn't apply.
- For anyone still at school, check their age, the permit and the hours, paid or not.
- Keep a notebook of real family hours for four weeks.
- Check the pay of any partner or spouse on your payroll against £129 a week, or £559 a month.
- Ask your accountant three things: is the rate commercial, can you claim the Employment Allowance, and should shares for a spouse be on the table at all.
- Read your employers' liability schedule against the exemption's limits.
- Put the hours in your wage percentage, and cost new hires with the new hire calculator.
Family help is one of the good things about an independent café. It's just worth knowing what it is in law, and what it's worth in your numbers.
Ed O'Brien has run Hunters Cake Company for 17 years across cafés in Witney, Burford, and a bakery in Carterton, Oxfordshire. He's building Brikly - modular tools that give independent café owners the same data the big chains have, without the big chain price tag.